
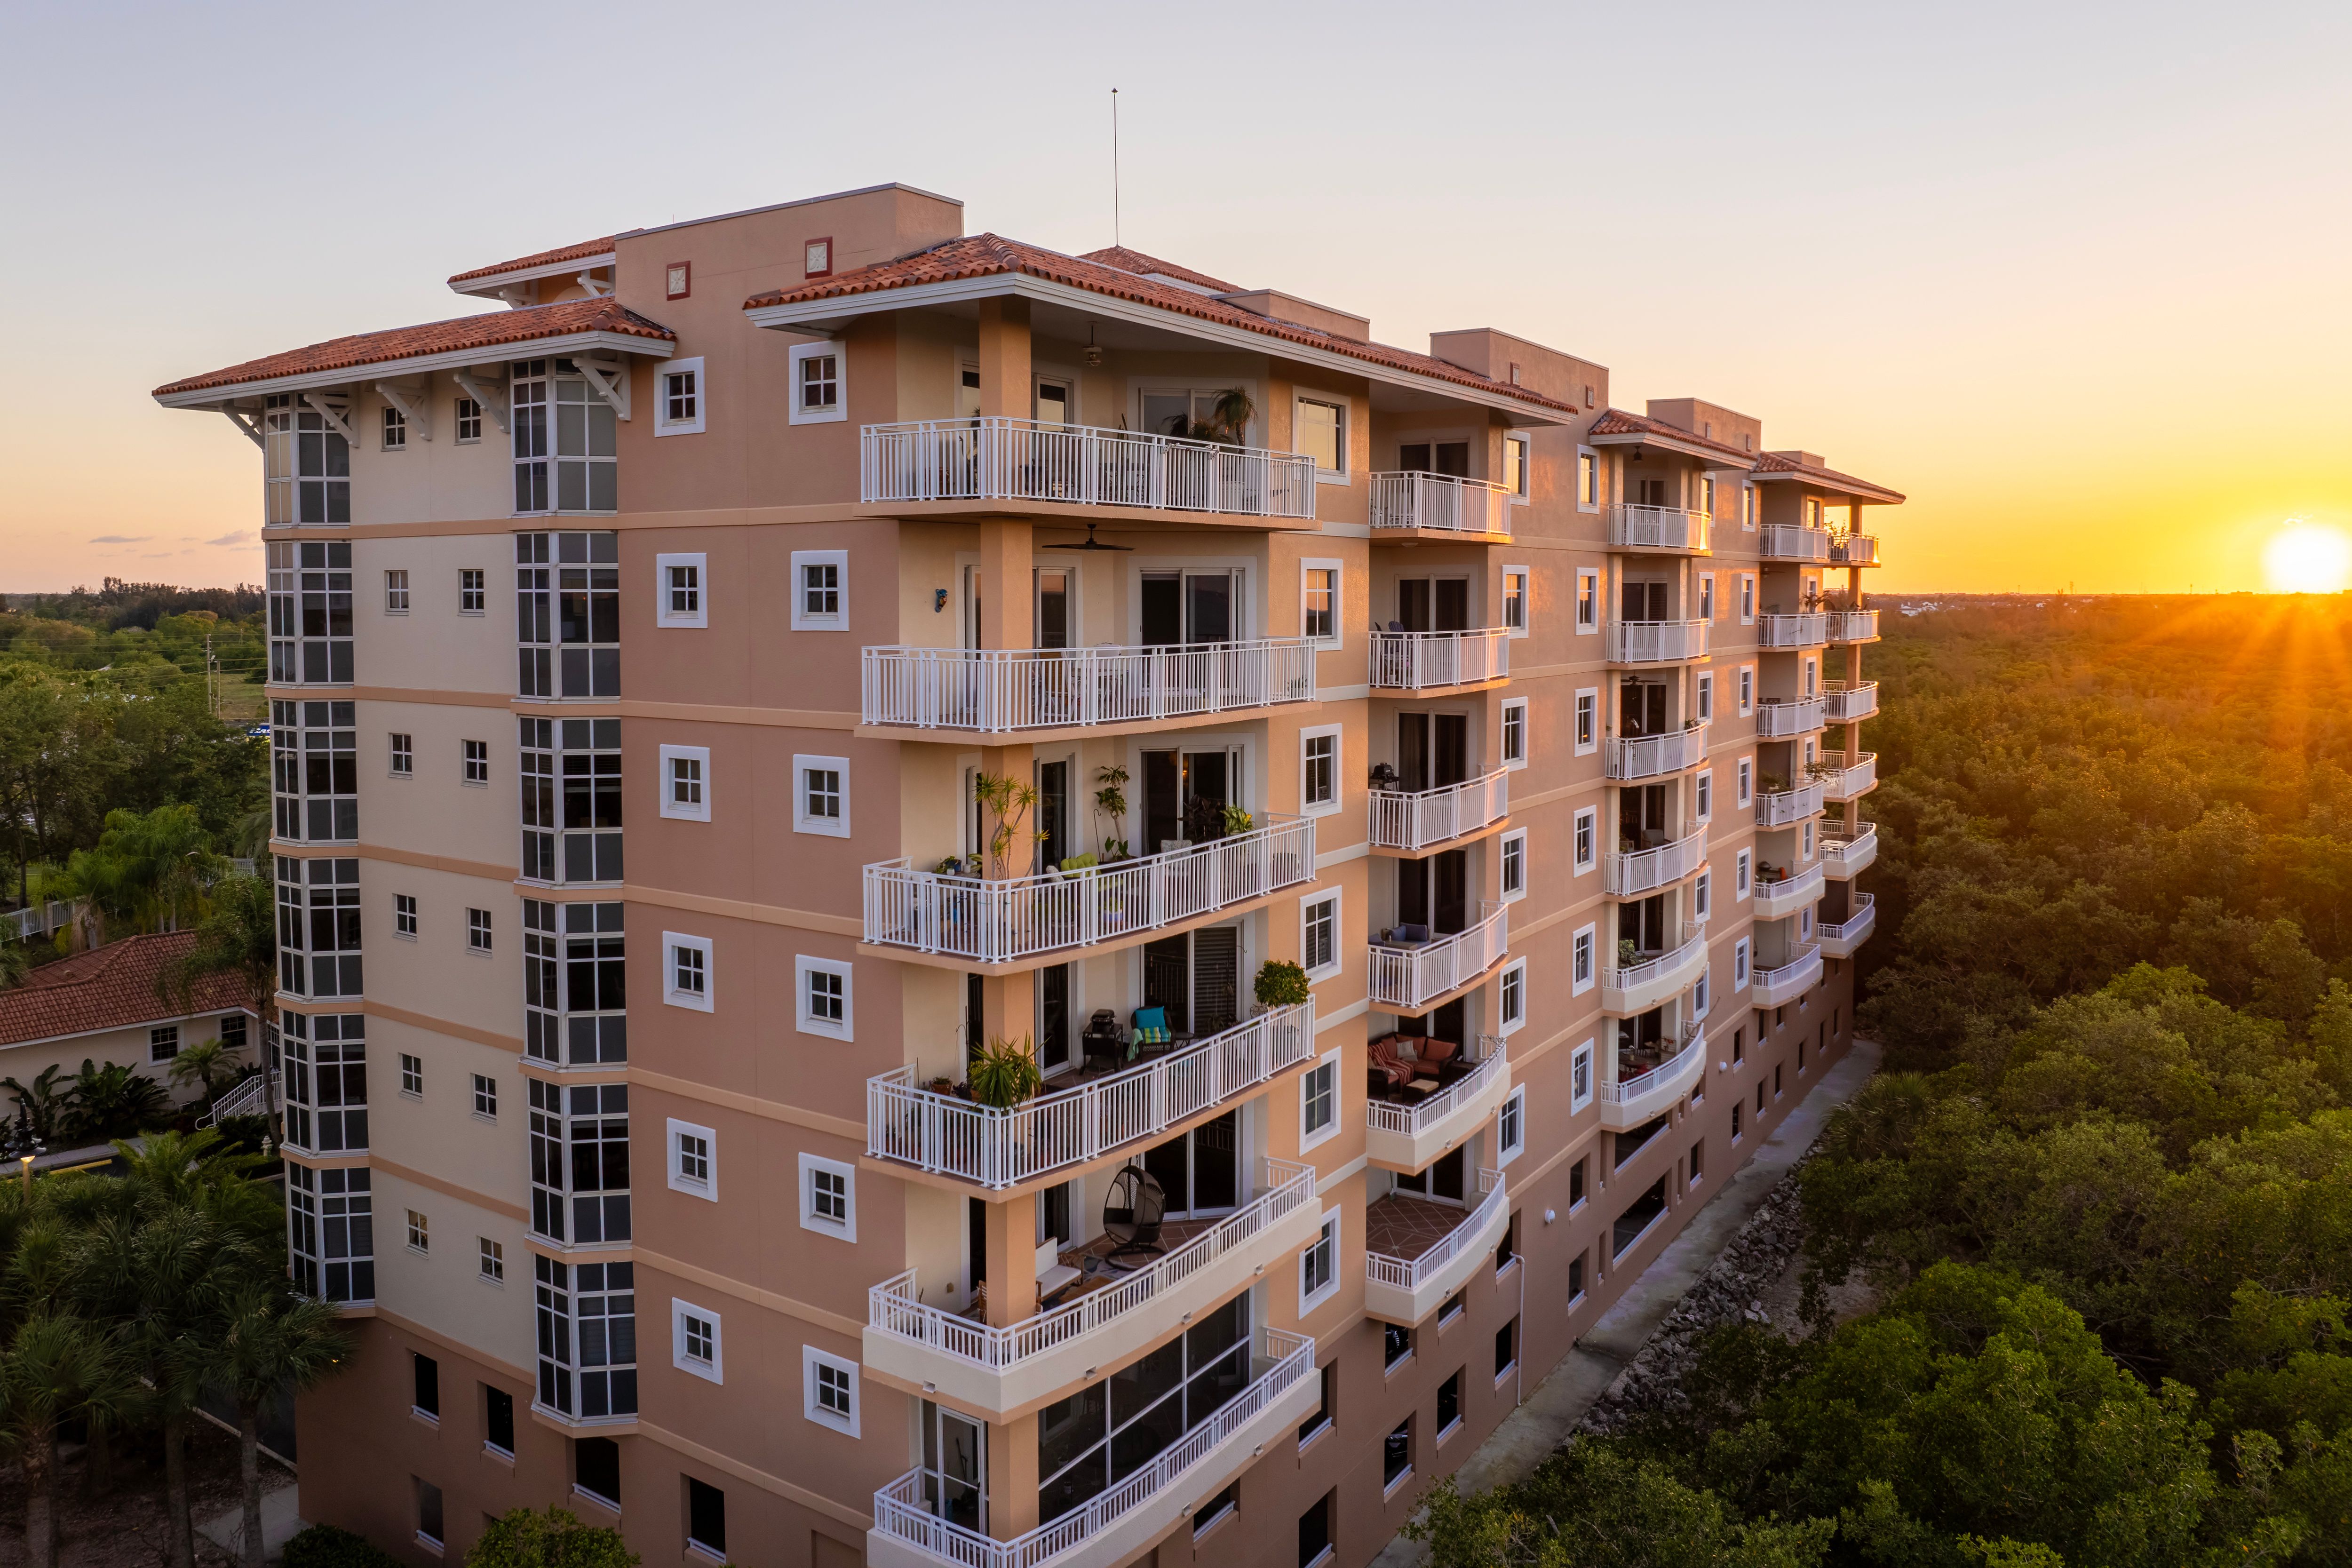
The letter came in a plain envelope with your association's return address, and the number inside was five figures. Now you are at a kitchen table in Michigan or Ohio or Ontario deciding whether the place you bought for winters on the Gulf is still worth owning.
If you are asking "should I sell my Florida condo in 2026," you are being responsible, not dramatic. Special assessments in Pinellas County are not random bad luck anymore. They are the predictable result of state law forcing buildings to fund repairs they deferred for decades, and the bill is landing on owners who use their unit four months a year.
This guide is a framework, not a sales pitch. By the end you will know what your condo actually costs you every year, the five questions that decide sell versus hold, and how to price the unit if you move on.
The Pinellas Condo Market in 2026: What the Numbers Actually Say
Pinellas condos are in a buyer's market while Pinellas houses are not. According to the March 2026 Pinellas County market report from Florida Realtors and the Suncoast Tampa Association of Realtors, townhouses and condos carried 8.1 months of supply that month against 3.8 for single-family homes. Florida Realtors economists treat 5.5 months as balanced, with anything above it favoring buyers.
That gap explains most of what owners are feeling. More from the same report:
- 4,163 active condo and townhouse listings countywide, 1,138 of them under $200,000, a segment up 10 percent year over year
- A median 58 days from listing to contract, and 95 days from listing to closing
- Sellers receiving a median 92.8 percent of their original list price
- 55.3 percent of condo sales closing in cash
Read that last one twice. More than half of Pinellas condo buyers are not using a mortgage at all. Financing has become the bottleneck, and cash buyers know it, which is why they negotiate the way they do.
Here is the part the headlines get wrong. The median Pinellas condo sale price that month was $295,000, up 7.3 percent year over year. Prices are not collapsing. The market has split. Well-funded buildings with completed inspections trade close to ask. Buildings with unfunded reserves, an open milestone finding, or a live assessment sit, cut, and eventually sell to cash investors at a discount. The county average hides both stories.
Your unit is in one of those two groups. Figuring out which one is the whole job.
Step One: Add Up Your True Florida Condo Carrying Costs
Most owners underestimate this by thousands because they only count the dues. Work all eight lines using last year's actual statements, not what you remember paying.
- Monthly association dues, annualized. Use the current figure, not the one from when you bought. A Redfin analysis of MLS listings found Tampa metro median monthly HOA dues rose 17.2 percent year over year in the three months ending July 31, 2024, the steepest jump among the 43 metros it tracked, against a 5.7 percent median across those markets.
- Your current assessment, spread across its payment term. If you owe $42,000 over 36 months, that is $14,000 a year and it belongs here as a real cost.
- Reasonably expected future assessments. Open your SIRS funding plan and find the components with under ten years of remaining useful life. Those are next. If the reserve balance behind them is thin, write down a number instead of pretending it is zero.
- Your HO-6 unit owner policy, covering interior, contents, and liability, separate from the association's master policy.
- Flood coverage. First Street data on Redfin's Pinellas County market page identifies 102,859 properties, 42 percent of everything in the county, as likely to be severely affected by flooding over the next 30 years. Ground-floor and low-elevation units carry the most exposure.
- Property taxes, at snowbird rates. This is where out-of-state owners get surprised. You have no homestead exemption and no 3 percent Save Our Homes cap. The Pinellas County Property Appraiser explains that non-homestead property is limited to a 10 percent annual increase in assessed value, and that the cap does not apply to school district taxes at all. Your full-time neighbor is protected at 3 percent. You are exposed to more than triple that.
- Year-round fixed costs on a part-year home. Electric and water minimums, internet, pest control, storm prep, and whatever you pay someone to check the unit during the eight months you are gone.
- The opportunity cost of your equity. A paid-off $400,000 unit is $400,000 not invested elsewhere. You do not have to treat that as a hard cost, but you cannot pretend it is free either.
Total the eight lines, then divide by the months you actually use the place. That is your real cost per month of occupancy, and it is the number this decision turns on.
The Five Questions That Decide Sell or Hold
1. Is your building compliant, and is the SIRS funded?
Florida's structural integrity reserve study requirement applies to residential condo buildings three or more habitable stories tall, repeated at least every ten years. HB 913, effective July 1, 2025, extended the initial completion deadline to December 31, 2025, raised the reserve threshold for non-listed components from $10,000 to $25,000, and gave boards more ways to fund reserves, including loans and lines of credit with owner approval.
The provision that matters most to you sits in Florida Statutes 718.112. For budgets adopted on or after December 31, 2024, owners in an association required to obtain a SIRS can no longer vote for no reserves or reduced reserves on the covered structural components. The old escape hatch of voting reserves down to keep dues low is closed.
Ask your manager for three documents: the completed SIRS, the most recent milestone inspection report, and the current-year budget showing what is being funded against the study's plan. A building with all three, funding on schedule, is a fundamentally different asset from one still "working on it." For a plain-English walkthrough of these studies, see what a SIRS is in Florida.
2. Is this assessment the last one or the first one?
A one-time assessment for a roof, on a building otherwise funding its plan, is an inconvenience. A first assessment on a building with a decades-long history of waived reserves is the opening payment on a much larger obligation.
Read two years of board minutes and look for words like deferred, tabled, phase one, and engineer's recommendation. If phase one is being assessed now, phases two and three exist somewhere in a report. Our breakdown of Florida condo special assessments and 9 red flags covers what to look for line by line.
3. Can a buyer actually get a mortgage on your unit?
This question quietly destroys value, and most owners never think to ask it.
Fannie Mae keeps a confidential list of condo projects ineligible for its financing. Data obtained by the law firm Allcock Marcus and reported in early 2025 put 1,438 Florida condo buildings on that list, 696 of them in Miami-Dade, Broward, and Palm Beach counties alone. Owners in flagged buildings find it close to impossible to sell to anyone who needs a conventional mortgage.
If your project is flagged, your buyer pool shrinks to cash and portfolio lenders. That is the mechanism behind the 55.3 percent cash share in the county data, and it is worth several percentage points of price. The list is not public, but your board or property manager can check the project's status. Do not wait until a buyer's loan dies in underwriting to learn the answer.
4. What does one more year of holding cost against realistic appreciation?
Compare your total annual carrying cost against what one year of appreciation would plausibly add to your unit's value. If carrying costs run $28,000 a year on a $350,000 condo, you need roughly 8 percent annual appreciation just to break even on holding, before selling costs. That is a demanding number in a segment sitting at 8.1 months of supply. Not impossible in a strong building in a strong location, but it should be argued, not assumed.
5. Are you still using the place the way you planned to?
The financial analysis only takes you so far. Owners who come down for four full months, know their neighbors, and would otherwise pay peak-season rental rates get real value no spreadsheet captures. Owners who came down twice last year for ten days are paying resort prices for storage. Be honest about the last two winters, not the ones you intended to have.
If you want a second read on where your building sits, reach out to Eagan Luxury. We track assessment activity and buyer behavior building by building across St. Petersburg and the Gulf beaches.
Two Owners, Same Era of Building, Opposite Answers
These are illustrative scenarios rather than client transactions, but the arithmetic is real.
Consider a couple from Cleveland who bought a two-bedroom Gulf-front unit in a 1988 building for $310,000 in 2016. The milestone inspection came in late, the SIRS showed significant concrete restoration, and the board assessed $61,000 per unit over four years. Dues climbed to $1,050 a month. Annual carrying cost now runs past $33,000 including assessment installments and non-homestead taxes. They visited for six weeks last winter, and conventional financing is unavailable because of the open repair scope. Holding means paying roughly $132,000 over four years for a unit whose value will not recover until the work is finished and the building is warrantable again. The honest question is whether they can stomach a lower price now to stop a larger bleed, and both paths belong in front of their CPA rather than defaulting to hold because selling feels like defeat.
Now consider a couple from Toronto in a 2004 building two miles inland. Their SIRS was completed in 2024, reserves are funded on plan, and their new assessment is $9,400 for a roof the study projected years ago. Dues are $640. They spend January through April there every year. Carrying cost is high, but use is high, the building is financeable, and the assessment is a scheduled event rather than a warning sign. Selling into an 8.1-month market to dodge a planned $9,400 expense would be the expensive decision.
Same county, same era of condo law, opposite answers. Building condition and actual use separate them.
If You Hold: Four Moves That Protect Your Position
- Get into the room. Owners who read the financials before the vote have influence. Owners who read the assessment letter have none.
- Push for a SIRS-aligned funding plan over repeat emergency assessments. Predictable dues protect resale value far better than artificially low dues ever did.
- Confirm your project's lending status every year. Warrantability is now part of your unit's value, and it changes.
- Keep every receipt. Assessments funding capital improvements can affect your cost basis at sale, and reconstructing that paperwork years later is painful.
If You Sell: How to Price and Position a Pinellas Condo in 2026
Work through this in order before you assume anything about timing.
- Assemble the document package before you list. Current budget, reserve balances, SIRS, milestone report, two years of minutes, master insurance declarations, and a written statement of any assessment balance. Buyers ask for all of it, and sellers who have it ready win the negotiation on tone alone.
- Decide who pays the assessment, and put it in writing. Paying the balance at closing usually nets more than discounting the price by the same amount, because it removes an unknown from the buyer's underwriting.
- Price against the true comparable set. Not "units in my building" and not "condos in Pinellas." Units in buildings with a similar compliance and funding profile. A financeable unit and a cash-only unit are different products at identical square footage.
- Price to the first three weeks. With a countywide median of 58 days to contract, a listing that has not drawn serious interest inside 21 days is priced above its market, and every week after that costs more than the price cut would have.
- Target the buyer's calendar, not yours. Snowbird buyers tour in person from January through March. Listing in November with strong photography and a complete document package puts you ahead of that traffic instead of competing inside it.
- Disclose everything, early. Florida sellers must disclose known material facts affecting value that a buyer cannot readily observe, and a pending assessment is exactly that. Late disclosure kills deals at inspection. Early disclosure gets it priced.
The Tax Side of Selling a Florida Vacation Home
Talk to your CPA before you list, not after you close. Two points shape most snowbird sales.
First, the exclusion probably does not apply to you. The IRS explains in Topic no. 701 that the $250,000 and $500,000 home sale exclusion requires meeting both an ownership test and a use test: owning and using the home as your main home for at least two of the five years before the sale. A winter condo used four months a year does not meet the use test, so the gain is generally a taxable capital gain. Full rules and worksheets are in IRS Publication 523.
Second, your basis is probably higher than you think. Capital improvements and capital-improvement assessments you have paid can raise it, which reduces the taxable gain. That is the best reason to have kept those receipts. If the unit has been rented rather than used personally, a 1031 exchange may also be on the table, which is a different conversation and one to have well before you have a contract.
The Bottom Line: Should You Sell Your Florida Condo in 2026?
Should you sell your Florida condo in 2026? The answer is not about the market. It is about your building and your use. Add up all eight carrying cost lines. Pull the SIRS, the milestone report, and the budget. Find out whether a buyer can get a loan on your unit. Then weigh one more year of holding against what appreciation can realistically deliver in a segment carrying 8.1 months of supply.
Owners in funded, financeable, well-run buildings who genuinely use the place should usually hold. Owners in buildings that deferred maintenance for twenty years, are paying for it now, and visit twice a winter usually find the math has already decided. The mistake is not selling, and it is not holding. It is choosing without running the numbers.
If you want a candid read on your building, your unit's realistic value today, and what each path looks like in dollars, contact Eagan Luxury. We will tell you if holding is the better call.
Frequently Asked Questions
Is now a good time to sell a Florida condo?
It depends almost entirely on your building. Pinellas condos and townhouses carried 8.1 months of supply in March 2026, with sellers receiving a median 92.8 percent of original list price, which favors buyers countywide. But well-funded, financeable buildings with completed inspections still sell close to ask. Discounts are concentrated in buildings with open structural findings or unfunded reserves.
Will Pinellas condo prices recover once buildings finish their assessments?
Buildings that complete repairs and restore reserve funding typically regain conventional financing eligibility, which widens the buyer pool and supports price. That process usually takes years, not months, and owners pay the full assessment plus elevated dues along the way. Recovery for any specific building depends on its repair scope, reserve position, and lending status.
Do I have to disclose a pending special assessment when I sell?
Yes. Florida sellers must disclose known material facts that affect value and are not readily observable to a buyer, and an approved or pending assessment falls squarely in that category. Association estoppel documents surface the balance during the transaction anyway, so early written disclosure protects you and keeps the deal intact.
Can I sell my condo if the building is on Fannie Mae's ineligible list?
You can, but almost always to a cash buyer or one using portfolio financing. Reporting in early 2025 identified 1,438 Florida condo buildings as ineligible for Fannie Mae backing, and owners in those buildings find it close to impossible to sell to buyers who need conventional financing. A smaller buyer pool generally means a lower price and a longer timeline.
Do I pay capital gains tax when I sell my Florida vacation condo?
Usually yes. The IRS home sale exclusion requires that you owned and used the property as your main home for at least two of the five years before the sale, which a seasonal condo typically does not satisfy. Capital improvements and capital-improvement assessments you paid can raise your cost basis and reduce the taxable gain, so bring that documentation to your CPA.
About Debi Eagan
Expert real estate agent specializing in St. Petersburg and surrounding areas. Helping families find their dream homes with personalized service and local market expertise.
Contact Debi Eagan